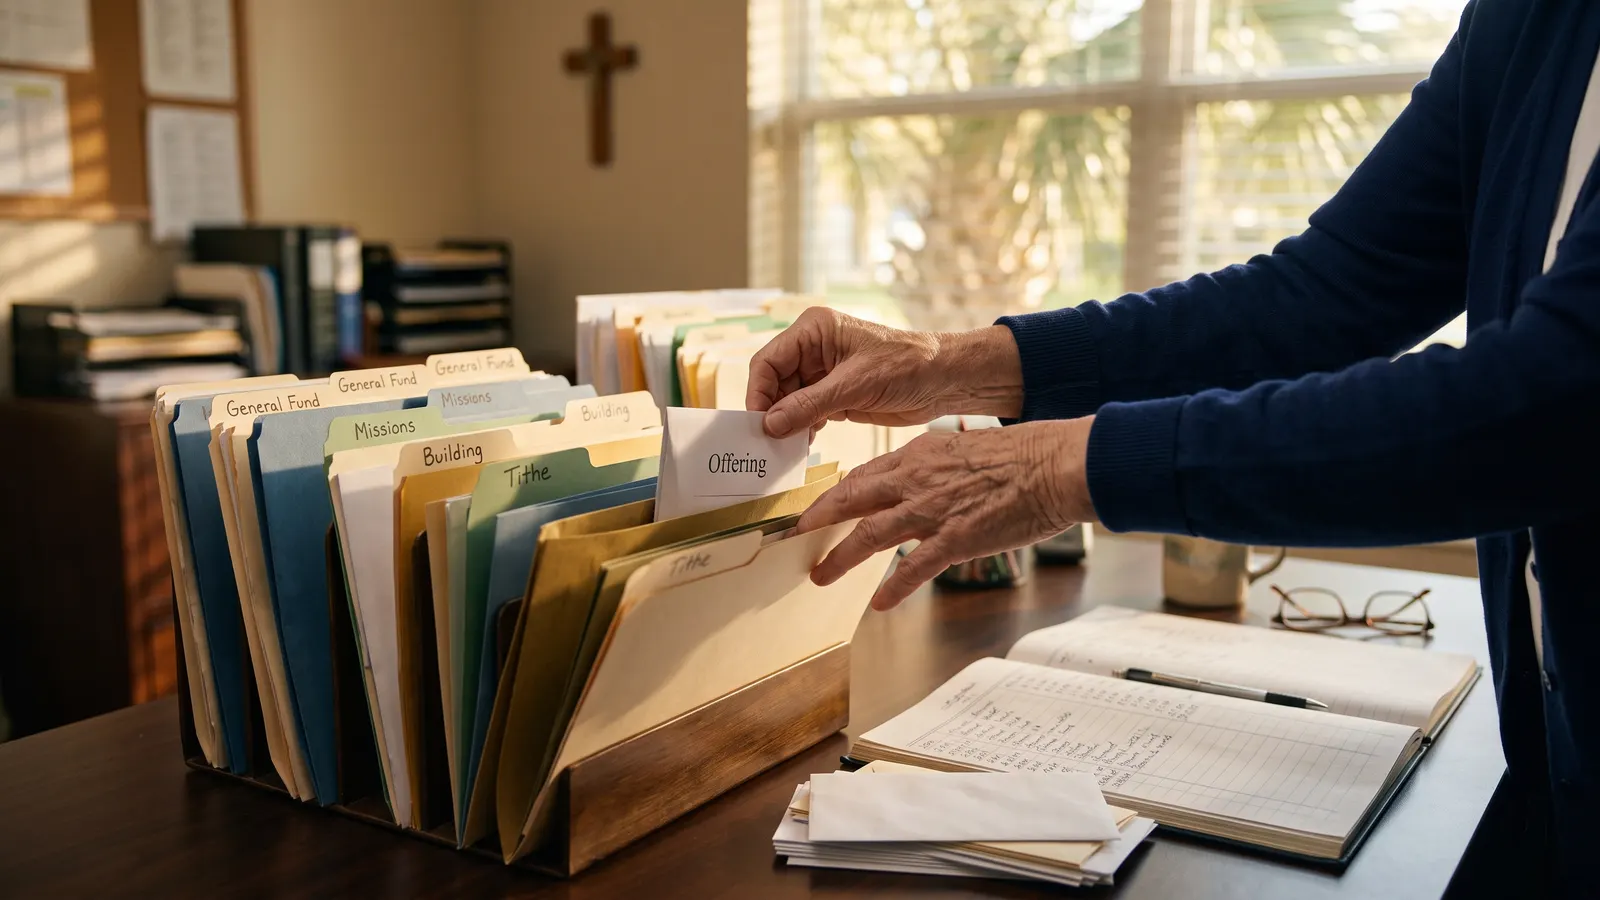
A donor gives to the building fund. A family gives in memory of a loved one for youth ministry. The board sets aside money for a future roof. Each of these is a promise, and the books have to keep that promise visible.
Tracking these funds well is one of the eight areas in the Ministry Financial Blueprint, and one of the first places boards find surprises.
The two kinds, in plain terms
Restricted funds are gifts the donor directed to a specific purpose. Designated funds are amounts the board or leadership set aside from unrestricted money for a purpose of its own choosing. The difference matters: leadership can change a designation, but it cannot change a donor’s restriction without going back to the donor. Your CPA or attorney can advise on the specifics for your organization.
Track them separately, always
- Give each fund its own account or class in your accounting system, so its balance is visible at any time.
- Record gifts to the fund when they come in, and spending from the fund when it goes out, against that fund only.
- Keep the detail: donor, date, purpose and any written instruction.
- Reconcile the fund balances each month as part of the close, so the total of all funds ties to the cash and investments that back them.
The most common mistake
Using restricted money, temporarily, to cover general operating expenses. It usually happens quietly: cash is tight, one bank account holds everything, and the general fund borrows without anyone deciding to. The fund balances still show on paper, but the cash behind them is gone.
The fix is visibility: a monthly report that shows each fund’s balance next to the unrestricted cash actually available. When leadership can see that unrestricted cash is lower than the fund balances, the conversation happens before the problem grows.
What the board should see each month
- Each restricted and designated fund: opening balance, gifts in, spending out, closing balance.
- Total fund balances compared with total cash and investments.
- Unrestricted cash truly available for operations, after the funds are set aside.
- Any fund that has been inactive for a long time, so leadership can decide what to do about it with proper advice.